First Home to First Rental.
Your first home can be the start of something bigger. The down payment math, how to buy with the rental already in mind, and when it makes sense to buy the next one.
- Free
- For buyers
- Worksheet included
11 pages · 5 parts · worksheetFrom a Top 100 Real Estate Agent in New York
“Jamie is a total rockstar! Not only does she know her stuff she is truly one of the kindest and most thoughtful professionals I have ever worked with.”
Kristen M. · First-time buyer · Client review
I have this conversation with buyers every week.
Most people buy their first home like it's the last house they'll ever own. The buyers who build real wealth buy it like it's the first property they'll ever own. I walk my clients through that plan before we ever tour a house. This playbook is that plan.
Jamie Jamie Mazuryk, Top 100 Real Estate Agent in New York
A real playbook. Not a blog post.
Designed to be printed, marked up and kept by your desk. Here is what is inside, and what each piece saves you.
- Buy your first home like a first investment.
The playbook
11 pages, 5 parts, the plan I walk buyers through before we tour a house.
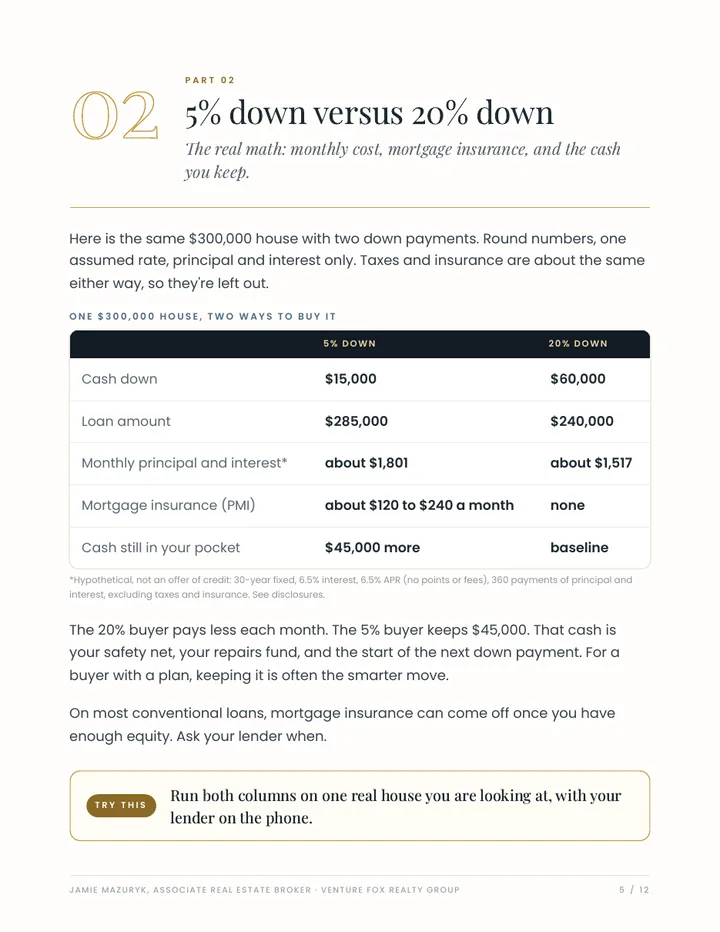
- See the $45,000 difference before you decide.
The 5% versus 20% table
One $300,000 house, both ways: cash down, monthly cost, insurance, cash kept.
- Avoid a house that only works for you.
The rent-ready checklist
Layout, location, well and septic: what makes a home easy to rent later.
- No surprises when you are ready to rent it.
Questions for your lender
The three questions most buyers never ask, including how long you must live there.
- Know the number that says it is time.
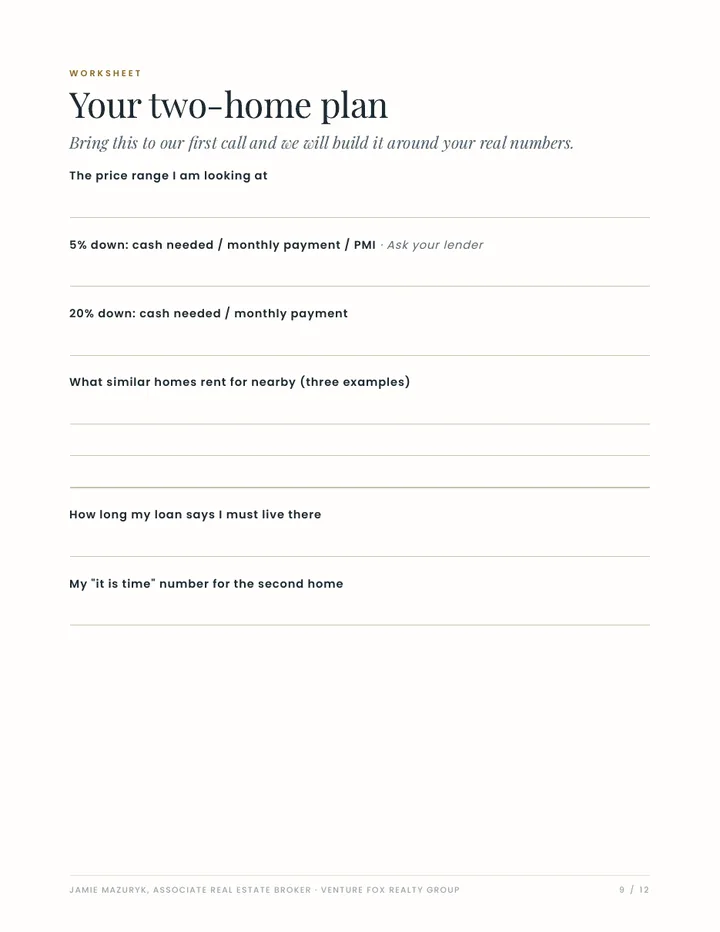
Your two-home plan worksheet
Bring it to our first call and we build it around your numbers.
- Free
Your price
Your first name and email. No call, no pitch.
Five parts, from the first home to the second.
Each part ends with one number to write down.
- 01
Your first home is your first investment
Buying with the next step in mind changes what you buy.
Try thisWrite down where you want to live in five years, not just next year.
- 02
5% down versus 20% down
The real math: monthly cost, mortgage insurance, and the cash you keep.
Try thisRun both columns on one real house you are looking at, with your lender on the phone.
- 03
Buy with the rental in mind
Layout, location and numbers that make a home easy to rent later.
Try thisFind three homes like the one you want that are listed for rent nearby, and write down the rents.
- 04
The rules most buyers never hear
Occupancy, timing, and what your lender will want to see.
Try thisAsk your lender, in writing, how long you need to live in the home first.
- 05
When to buy the second one
The signs you are ready, and the order to do it in.
Try thisSet the one number that tells you it is time, and write it at the top of the worksheet.
- You are buying your first home in the next year or two.
- You already own and wonder if it could be a rental.
- You want a plan, not just a house.
- You want someone to talk you into more house than you can afford. I will not.
Yours in about a minute.
Get it
Enter your name and email. It opens right away, free.
Run the numbers
Use the 5% versus 20% worksheet on a real house.
Bring it to our first call
If you want a plan built around your numbers, bring the worksheet.
Questions
Do I need a lot of money to start?
No. That is the point of the 5% versus 20% part: what you actually need, and what it costs you either way.
I already own a home. Is this still useful?
Yes. Parts 4 and 5 are about turning the home you have into a rental and buying the next one.
Is this legal or financial advice?
No. It's how I explain these things to my own clients, written down. Every deal is different, so talk to your attorney, lender and tax professional before you act on it.
Buy the house. Build what comes next.
Your first name and email, and it is yours in seconds. No call, no pitch.
Down payment and payment figures in this playbook are hypothetical examples, not an offer or advertisement of credit. They assume a 30-year fixed-rate loan at 6.5% interest (6.5% APR, no points or fees), 360 monthly payments of principal and interest, excluding taxes and insurance. Terms and eligibility depend on the loan program and your credit; only a licensed lender can quote real terms.